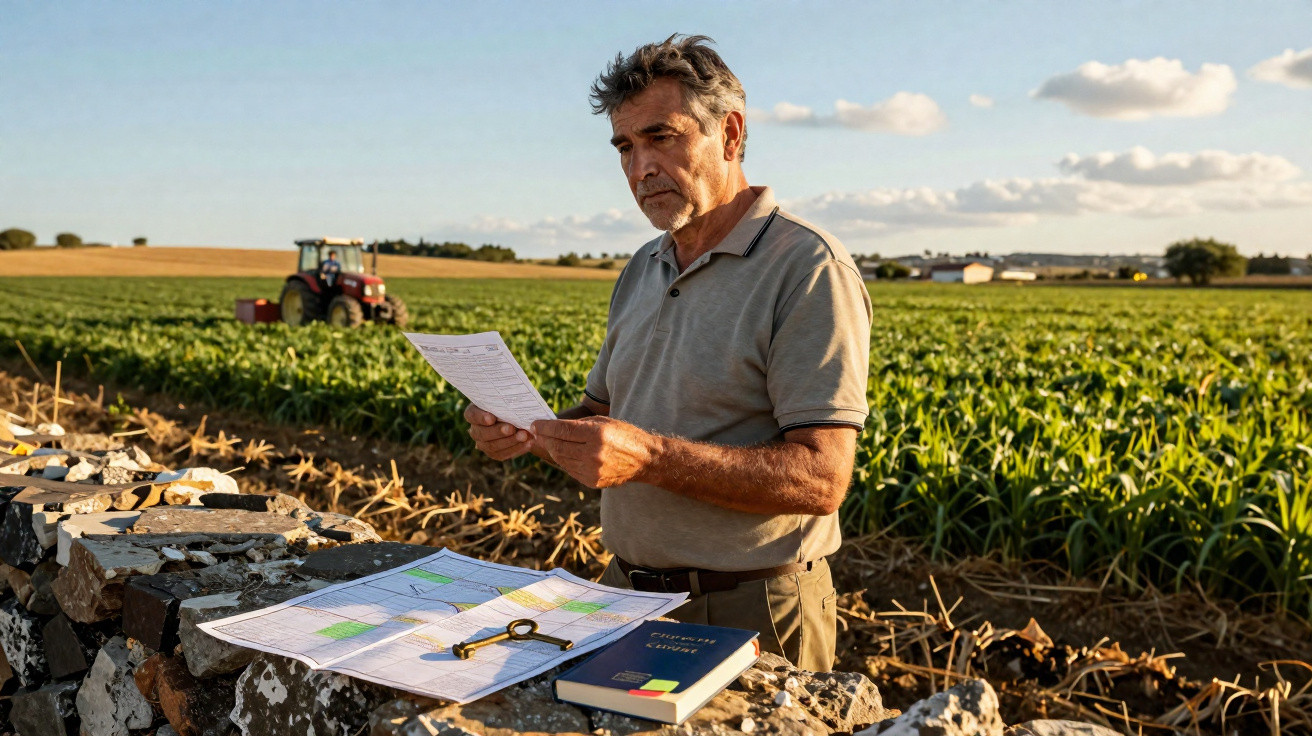
The notice came on a Tuesday, creased in half like a low-cost takeaway menu.
Its front bore the state seal, a barcode and four words that immediately tighten your stomach - “Amount due upon receipt.”
Inside, Martin, a 63-year-old landowner, found a tax demand that seemed utterly illogical. The farmland behind his modest home had passed to him from his parents. He does not cultivate it. He does not let it for rent. Instead, he allows his neighbour to grow a little wheat there free of charge, just as his father did during the 1980s.
So why had the tax office, this year, abruptly decided that this neighbourly arrangement was a commercial transaction?
The land was unchanged.
The people were unchanged.
What had changed was the state’s assessment of its value.
When “free” use of your land suddenly looks taxable
As a landowner, you may assume the arrangement is straightforward.
You pay property tax because the land belongs to you, rather than because another person crosses it or grows potatoes on it.
But tax authorities worldwide are taking a stricter approach to their interpretation of “use” and “benefit”. The principle may appear technical on paper, yet it becomes very tangible when the demand arrives through your letterbox. Where a third party cultivates your land, even without paying rent, the state may claim that this activity increases the land’s economic value.
For tax purposes, that “value in use” may be sufficient to raise your taxable base.
Overnight, a kind favour for a neighbour becomes more than an act of goodwill.
It becomes an entry in a tax calculation.
Consider a familiar rural situation.
A retired couple own 15 hectares which they no longer have the physical ability or machinery to work.
Their neighbour, a young farmer struggling with loan repayments, asks to plant barley on part of the plot. There is no agreement. No rent. Only: “Use it, it’s better than letting it go to weeds.” For three years, the arrangement suits everyone. The land is looked after, the village appears less deserted, and the couple feel they are supporting a younger generation.
Then the local authority revises the values in its land register. Satellite photographs, crop declarations and agricultural subsidy information indicate that the land is being actively cultivated. The tax rate is reassessed. The couple’s property tax rises by 25%.
Puzzled, they telephone the tax office.
The response is stark: “Your land is productive agricultural land. That’s what we tax.”
In the state’s view, this has nothing to do with your individual generosity.
It concerns the land’s objectively assessed potential.
Tax rules in numerous countries quietly rest on two concepts: ownership and the ability to generate revenue. When land is cultivated, even by another person, the system regards it as having income-producing capacity. Depending on the system, this may result in higher land valuations, agricultural land supplements or imputed-income classifications.
Whether you actually receive any money from it does not always matter.
This is where the surprise lies. People expect tax to follow cash actually received.
Tax law frequently follows potential income, rather than money that has genuinely changed hands.
On paper, that may seem rational. For someone like Martin, however, it feels like being taxed on a profit he never received.
How to protect yourself when someone farms your land “for free”
The first practical step is straightforward, although surprisingly few people take it.
Put the arrangement in writing.
Where a neighbour or family member uses your land, even where no rent is charged, you can prepare a simple “loan for use” agreement - a free-use contract confirming that no payment is made and that you retain control of the land. In certain legal systems, this can help demonstrate that you are not operating an undisclosed rental business.
You may also keep a record of the land’s use: grazing, small garden plots or occasional hay cutting.
Land uses are not all treated alike.
The more limited and clearly non-commercial the activity appears, the easier it may be to challenge an overly forceful tax reclassification later.
The greatest risk is saying nothing.
When no one discusses the arrangement, everybody assumes the law will view it as “just helping each other out”.
Yet tax inspectors do not come into your kitchen to hear the history behind it. They look at maps, land classifications and, at times, crop information. Where any uncertainty exists, they generally adopt the interpretation that produces more tax. That’s how you end up paying for income that only exists in their spreadsheets.
We have all experienced that point when a neighbourly handshake made years earlier suddenly seems like a legal issue.
Before the matter develops further, seek advice from the local tax office or an agricultural solicitor. A brief, unexciting meeting now may prevent a lengthy and acrimonious dispute later.
Let us be honest: almost nobody studies the whole tax code before allowing a neighbour to park a tractor or plant a field of sunflowers.
Tax specialists repeatedly give puzzled landowners the same advice:
“From the moment your land is demonstrably used in an organized, repeated way for production, the tax authority will tend to treat it as productive property, whether or not you receive rent.”
When examined closely, the state is generally interested in three points:
- Who is officially registered as using the land, on farming registers or subsidy applications
- Whether the owner and user have any written agreement, including a free one
- How the land is categorised in the cadastre or local planning records
Knowing how these three factors work gives you scope to respond.
Alter the classification, identify the user clearly or revise the agreement - and you alter how apparent your “free” arrangement is to the tax system.
Owning land between law, loyalty, and common sense
This situation centres on a conflict between two different realities.
On one side is a rural tradition of mutual support, in which land is shared as readily as tools.
On the other is a digitalised tax system that reviews aerial images, cross-references databases and almost never recognises the human relationships behind a maize field or a line of vines. The question, “Can the state really tax you because someone else farms your land for free?”, points to something broader: who decides what has value in our lives - communities or spreadsheets?
Some landowners will decide to formalise every arrangement, complete with contracts.
Others will discreetly stop lending their land, allowing it to become overgrown rather than face increased tax charges.
A small number will challenge the decision through an appeal, whether they succeed or fail.
Then there are those who will continue as their parents did, believing that generosity is worth a few additional lines on a tax bill.
You may not agree with them.
But you can understand them.
| Key point | Detail | Value for the reader |
|---|---|---|
| Clarify land use | Prepare a straightforward written “free-use” agreement and record who uses which land | Lowers the risk of being treated as though you receive undisclosed rental income |
| Know your land’s status | Check the cadastre and local zoning records to establish how your plot is officially categorised | Helps you foresee possible tax rises where land is considered productive |
| Ask before you act | Speak to a tax office or legal adviser before allowing someone to cultivate your land | Avoids unpleasant surprises and improves your position if you challenge a bill |
FAQ:
- Question 1 Can I really be taxed more just because a neighbour uses my land for crops, even if I do not charge rent? Yes, in many systems the state considers whether land is put to productive use, rather than simply whether you receive cash. Active cultivation may increase the official value or classification of your land, which can raise your property tax.
- Question 2 Would a written “free-use” agreement prevent the tax office from raising my bill? Not necessarily, but it helps establish that no rental income exists and explains the nature of the arrangement. It may be useful in discussions or appeals where the tax assessment appears excessive.
- Question 3 What happens if I leave my land fallow and nobody uses it at all? The state will usually tax it according to its classification, such as agricultural land, building land or natural land. Without productive use, there is often less basis for treating it as income-generating, although the underlying property tax still applies.
- Question 4 Can the person cultivating my land free of charge be considered the “real” user for tax or subsidy purposes? Yes, and this is often the position. They may declare the land for subsidies or in agricultural registers. The tax office can then use those declarations as evidence that your plot is productive land.
- Question 5 What should I do if I receive an unexpected tax rise connected to my land being cultivated? Request a detailed explanation of the reassessment, collect any agreements or evidence that no payment was made, and consider submitting a formal appeal within the legal deadline. A short meeting with a specialist can quickly establish whether the revised assessment can be challenged.
Comments
No comments yet. Be the first to comment!
Leave a Comment