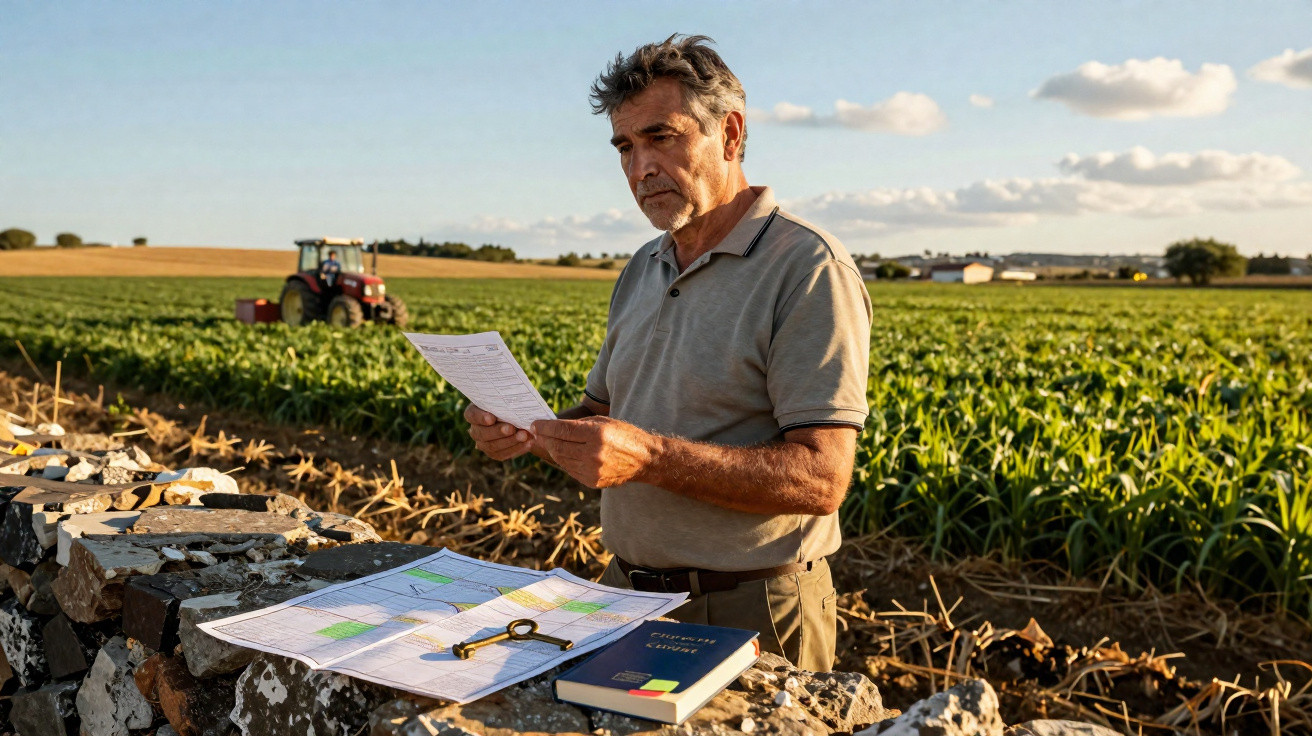
On a misty morning in March, when the horizon had vanished into a pale haze, Jean was walking his dog beside the boundary fence when his phone began to vibrate. The town hall number appeared on the display. He paused, rubbed his hand on his worn work trousers and answered. The caller sounded courteous, almost regretful: “About the land you lent to the beekeeper… there’s a tax issue.”
Jean stood still in the mud as his boots sank slightly further. At 72, he is a former factory worker whose joints have been worn down by decades of shifts, and he survives on a modest pension. He is not a farmer, sells nothing and does not “exploit” his 1.6-hectare plot. He simply allows a local beekeeper to keep several hives there, among the brambles and walnut trees.
Now the council wants him to pay a farming-related tax because of that “activity”. The bees labour for nothing, the beekeeper “isn’t making a cent” so far, and the pensioner is the only person being stung.
Somewhere between solidarity and freeloading, the boundary has been crossed.
When kindness becomes a tax demand
From the roadside, Jean’s field still resembles any other quiet parcel on the edge of a small town: a wonky gate, a rusty barrel and clumps of grass that stopped trying to look tidy years ago. Its only real movement comes from the muted buzz of bees and the beekeeper’s slow inspections of the frames on Sunday mornings.
Yet in official records, that same piece of ground has abruptly become an “agricultural use”. It is the sort of classification that triggers a programme in an office and adds a fresh entry to the tax register.
No official has actually visited the site. No one has touched the trees’ split bark or watched the beekeeper’s ageing van splutter up the incline. Instead, a single box has been selected on a form: hive installation = agricultural activity. Once that designation is made, the system seldom reverses it.
Cases like Jean’s are appearing increasingly often in smaller towns, where longstanding rural customs collide with newer tax instincts. A retired couple lends a section of field to a neighbour for vegetable plots, then finds that their land has been reclassified. A man permits a young farmer to graze three sheep to control the grass, only to discover that his property is now considered “in productive use”.
In south-western France, one widow allowed a young beekeeper just starting out to use a corner of her meadow. In the first year, no honey was sold: it was simply a learning period with bees. During the second year, a few jars were produced, most of them given away. In the third, she received a notice referring to “non-declared agricultural activity” on her land, along with a tax adjustment worth several hundred euros.
By urban standards, it may not sound dramatic. But for someone calculating every euro of their pension before month-end, that letter can feel like a blow to the chest. The beekeeper was deeply embarrassed, the town clerk uncomfortable, and the rules offered no flexibility.
The problem stems from a straightforward mechanism: as soon as land is used for any form of production, even on a tiny scale, it can fall into a category that attracts the attention of tax authorities. The original purpose was to stop people abusing the system by disguising profitable work as a “hobby”.
However, real life does not fit neatly into such labels. A retired owner lending an acre free of charge is not operating a business. A novice beekeeper with ten hives and no profit is not an agricultural enterprise absorbing subsidies. Still, both can be trapped by legal definitions designed for a very different setting.
The simple reality is that small rural favours which were once unrecorded and unseen are now being checked, classified and sometimes taxed. It leaves a bitter aftertaste unrelated to the honey.
Lending land to a beekeeper without being stung
For anyone considering letting a beekeeper or young farmer use a corner of their land, the most useful safeguard is unexciting but vital: a basic written agreement. It need not be elaborate or formally notarised. A single document should state plainly that the owner is not participating in an economic activity, that the arrangement is temporary and unpaid, and that the person installing the hives takes responsibility for their use.
One page and three signatures can be enough: the landowner, the beekeeper and, where possible, a local association or rural advisory service acting as witness. Include the start and end dates, the number of hives, and an explicit statement that there is no rent, no payment in kind and no undisclosed arrangement. This can make a substantial difference if the tax office begins asking questions.
It also makes people address points that are often overlooked: who reports what, who provides insurance, and what happens if neighbours object. They may be dry matters to set out in writing, but they safeguard the generous human act that prompted the agreement.
Many pensioners like Jean agree first with their hearts and never reach for a calculator. They notice a young beekeeper having a difficult start, recall a time when neighbours helped one another without forms, and open the gate. Months later, a letter arrives, leaving them feeling let down-not by the beekeeper, but by a system that appears to penalise generosity.
A common error is accepting honey or vegetables as “payment” without considering the implications. Once an exchange happens regularly, even if it is symbolic, officials may view it as rent. Another overlooked issue is planning classification: land designated in a particular way under the local plan may create specific obligations once it is “used”.
We have all experienced the moment when an uncomplicated favour turns into a stack of paperwork and telephone calls, making us wonder why we agreed in the first place. A short visit to the local tax office or a farmers’ association before lending the land can prevent unpleasant surprises later.
“I didn’t want a cent,” Jean repeats, shaking his head at the thought of that bill. “He gave me two jars of honey the first year, I almost didn’t take them. And now they treat me like I’m hiding some secret farm business.”
To stop goodwill turning into resentment, several simple precautions can help:
- Define the activity’s status clearly (hobby, test phase, micro-business, registered farm).
- Check with the town hall whether hives or crops alter the land’s tax category.
- Make any “thank you” gifts occasional and clearly symbolic rather than an agreed, regular return.
- Ensure that the beekeeper or farmer, rather than the owner, declares the activity.
- Record that the owner shares no profits, decisions or responsibilities relating to sales.
Solidarity, freeloading or something in between?
Long after the letters and tax-office appointments, one uncomfortable question remains: who is actually freeloading? Is it the pensioner who opens the gate for free and receives an unforeseen bill? Is it the beekeeper using another person’s land without taking on its hidden costs? Or is it a system that quietly converts every act of solidarity into a taxable opportunity?
The truth is less clear-cut than the anger suggests. Some landowners have indeed relied on supposedly friendly arrangements to conduct semi-hidden activities while avoiding tax. Some beekeepers and micro-farmers genuinely fail to appreciate how their projects affect those hosting them. And some authorities apply blunt rules to complicated lives because nuance takes time, and time costs money.
In truth, hardly anyone studies the entire tax code before agreeing to keep a couple of beehives at the edge of a field. It is in the gap between how people live and how the law assumes they live that these small tragedies take root.
This story resonates because it reaches something fundamental about rural life and trust between neighbours: the quiet network of favours, land lent “for now”, hives hidden behind barns and sheep grazing more through friendship than for profit. If every one of those connections begins to carry an unseen charge, something delicate may break.
Perhaps the real task is not choosing between solidarity and freeloading, but restoring the ability to help one another without being financially penalised. It is also about demanding rules capable of distinguishing between a pensioner with 1.6 hectares and a company exploiting loopholes hectare by hectare.
| Key point | Detail | Value for the reader |
|---|---|---|
| Put arrangements in writing | A simple agreement confirming free, temporary use and no shared profits | Lowers the risk of being reclassified as conducting an activity |
| Check local rules early | Ask the town hall and tax office how hives or crops affect land status | Prevents unexpected tax demands for pensioners and small owners |
| Keep favours as favours | Give symbolic gifts rather than regular “payment” in honey or produce | Helps maintain solidarity without causing hidden financial consequences |
Comments
No comments yet. Be the first to comment!
Leave a Comment