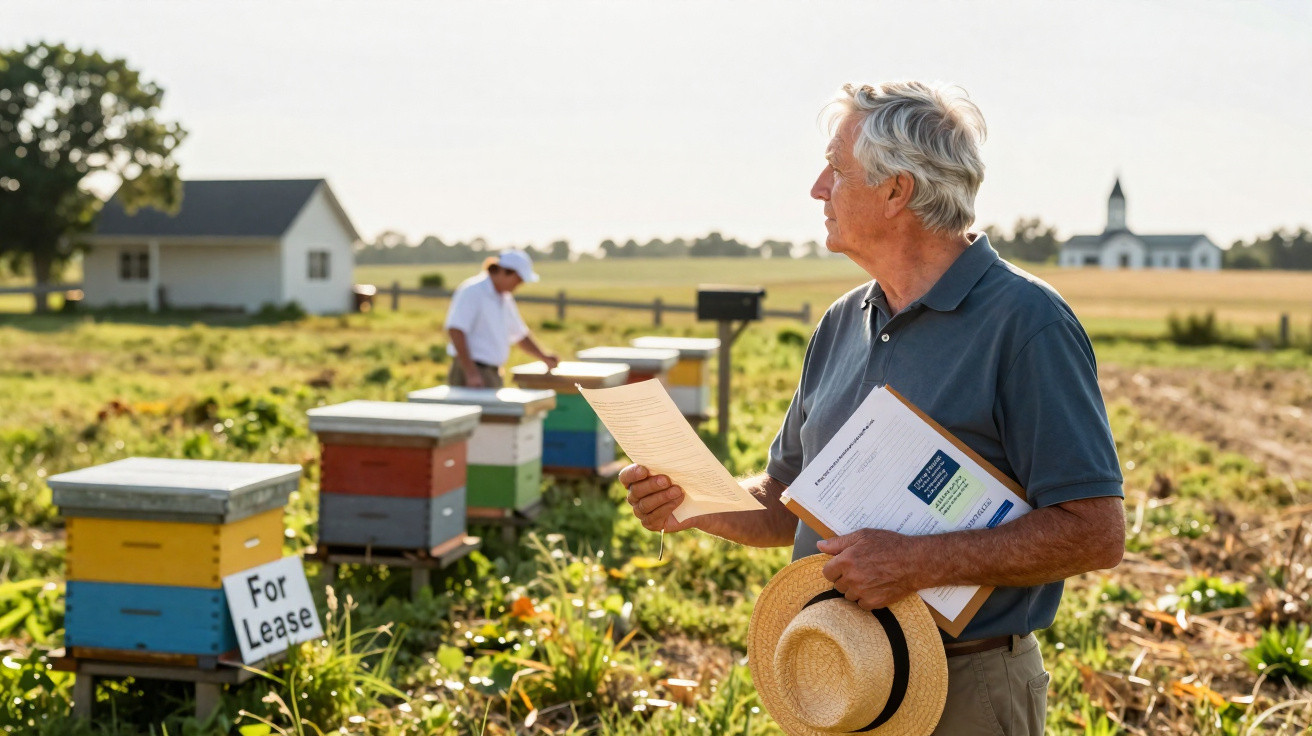
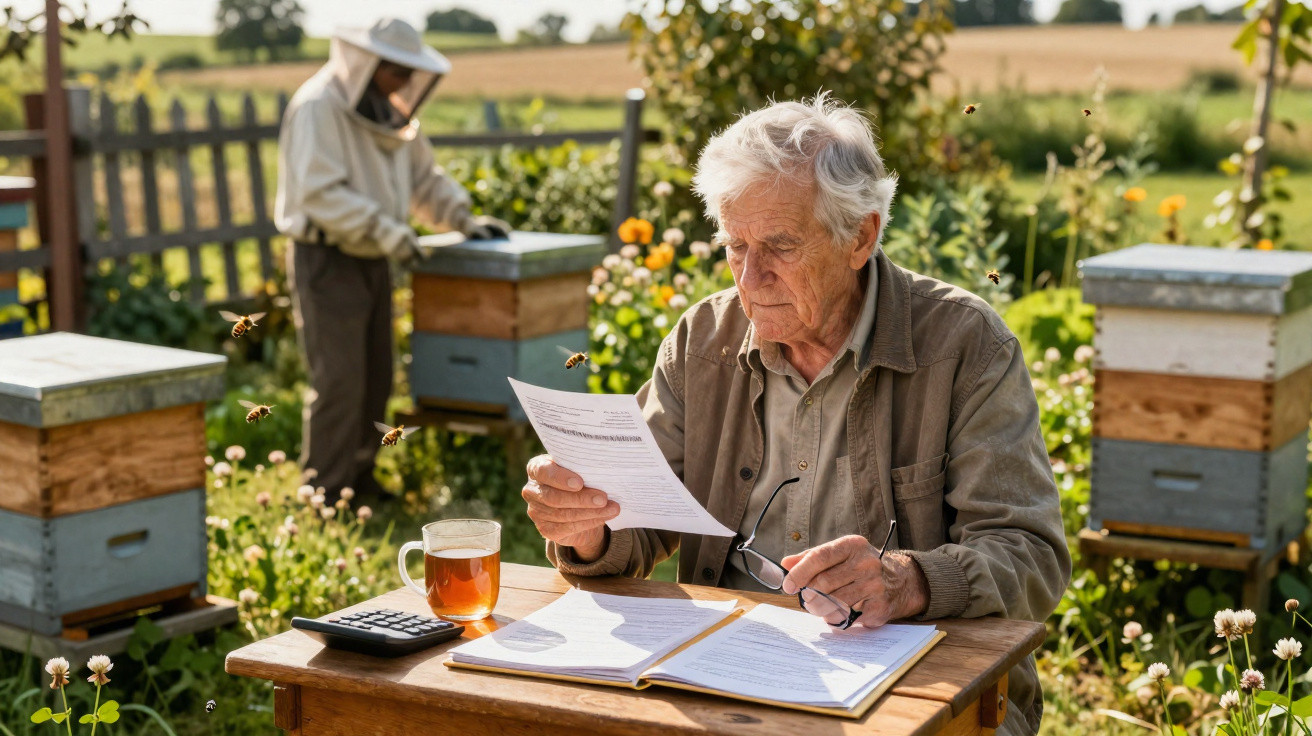
The morning the letter arrived, the retired man was tending his vegetable patch, hands deep in the earth as he tried to encourage a handful of late tomatoes through an unyielding summer. Hearing the postman’s scooter, he rubbed his hands on his trousers and went to the gate, expecting a bill or perhaps an advertising leaflet. What he found instead was a tightly written, impersonal sheet bearing the tax authority’s logo.
By the second paragraph, his jaw had genuinely fallen open.
After allowing a young beekeeper, who was struggling to save his hives, to use one corner of his land free of charge, the French authorities had classified him as… a farmer.
That designation brought retrospective social security contributions, a stack of paperwork as thick as a telephone directory, and the quiet indignity of being made to feel dishonest for an act of kindness.
He had only wanted to help the bees.
Instead, he had uncovered a legal hornet’s nest.
When lent land becomes “agricultural activity”
The tale began with bees rather than bureaucracy. One spring, a young local beekeeper called at the retiree’s home and asked whether he could keep several hives on an unused section of the property. The retiree had room, time and a natural sympathy for anyone trying to make something with their own hands. He agreed: no rent, no formal contract, simply a handshake across the fence.
For several months, that area of land contained little more than bees droning above the wildflowers and the rattle of the beekeeper’s ageing van coming up the track at daybreak.
No one realised that an administrative boundary had, on paper, just been crossed.
The problem emerged during a routine data cross-check. As a professional, the beekeeper had declared both his hives and the locations of his apiaries. One of those declared locations was the retiree’s plot. To the administration’s software, that connection activated a familiar classification: land being used for agricultural purposes.
After that, the machinery moved without intervention.
Letters were sent. Reference codes were allocated. In a database with little understanding of context, favours or agreements made across a fence, the retiree’s status shifted from “private individual” to “farm operator”.
He learned of his alleged new occupation only when the tax notice arrived through his letterbox.
On paper, the reasoning looks orderly. Land used for a professional purpose is automatically placed within agricultural or commercial classifications. Social security contributions follow those classifications. From an administrative perspective, the rules have to be applied consistently.
Real life, however, seldom fits neatly into those categories.
The same process can be triggered in villages where land is loaned for a community garden, where a neighbour keeps a few sheep on an unused plot, or where a local group grows vegetables “for everyone”. A declaration in one place and an automated match in another can turn an act of goodwill into a taxable event.
The system was designed to read form fields, not intentions.
How to be generous without falling into the tax trap
Once the story appeared in local newspapers, tax offices and town halls across the country began receiving calls. People were asking one question repeatedly: “If I lend a bit of my land, will I be treated as a farmer too?” Beneath the concern lies one straightforward habit to adopt before agreeing to let someone use your property for professional purposes.
Put. It. In. Writing.
Even a basic one-page agreement can make a major difference. It can explicitly confirm that the landowner is not carrying on an agricultural business, that no rent is being charged, and that the person using the land takes full responsibility for operating and declaring their professional activity.
Most people caught up in situations like this have done nothing improper. They have simply been trusting and informal, and may have had little appetite for paperwork. Naturally enough, they assumed a friendly arrangement would remain just that: friendly.
The difficulty begins in the gap between that instinct and the legal interpretation.
Before lending a field, a shed or even a long-term parking space for somebody’s food van, ask one clear question: “Are you going to declare this for your business?” If they say yes, your name and address are entering professional records.
Frankly, hardly anyone reads every piece of small print that accompanies that.
The experts who examined the retiree’s situation have all expressed the same point in different terms.
“The problem isn’t generosity,” one tax lawyer told me on the phone, “the problem is when generosity accidentally looks like co‑management of a business in the eyes of an algorithm.”
To prevent that misunderstanding, they recommend several practical and low-pressure measures that any landowner can take before lending space:
- Draw up a brief written agreement confirming that you are lending the land free of charge as a private individual and have no share in the profits.
- Ask the professional to record in their own paperwork that they are the sole operator and fully responsible for the activity.
- Retain copies of correspondence confirming that the arrangement is temporary and that you remain a non-professional landowner.
- Speak to your local mairie or a notary if the arrangement may continue for several years or concerns larger areas of land.
- Should a letter arrive from the authorities, reply promptly and calmly with the relevant documents, rather than ignoring it through fear.
The national debate: should good deeds cost money?
As news of the retiree’s position spread online, the matter became bigger than one individual’s case. People saw a familiar pattern: rules created for large farms and complicated businesses being applied, sometimes harshly, to small everyday acts. Social media filled with responses. Some insisted that “rules are rules”. Others viewed it as another example of a system unable to distinguish between a multinational company and a pensioner keeping bees at the far end of the garden.
One phrase, heard on a local radio programme, stayed with people: “When generosity becomes agriculture, we all lose a little faith.”
Elected representatives soon recognised that the issue carried an emotional significance well beyond a single tax demand. Several MPs called for clearer national guidance to safeguard informal acts of solidarity: land made available for beehives, for young farmers trying out a project, or for school-run educational gardens. Rural mayors described residents who had quietly abandoned similar plans after hearing about the beekeeper’s case.
No one wants to find their name in a database they cannot understand.
At the same time, farming union representatives cautioned against creating loopholes that would allow major operators to conceal genuine commercial use behind supposedly “friendly loans”. The delicate balance between supporting generosity and enabling abuse became central to a political tug-of-war.
Some who hear this story simply think, “Well, I’ll just stop helping strangers, that’s simpler.” Others reject that response completely. They say that, if the cost of a working tax system is the gradual disappearance of informal support, then perhaps the system should learn one or two new nuances.
In conversations on village benches and city balconies, the question broadens quietly: how should the law regard ordinary kindness? As a suspicious exception to be categorised and charged for? Or as a social good worth safeguarding, even if that creates a little more complexity?
One blunt observation keeps resurfacing in these discussions: rules that put people off doing good ultimately cost everyone more, simply in another currency.
What this story says about us
The retiree is likely to remember the sound of that tax letter landing on his table for longer than he remembers the peaceful pleasure of seeing bees thrive at the end of his field. His experience made administrators reconsider their own classifications. It also led neighbours to assess the risks before agreeing to help the next beekeeper, gardener or young farmer who comes to their door. In an oddly modern way, it gave fresh form to the old conflict between common sense and legal inflexibility.
We have all experienced that moment when an ordinary favour suddenly comes up against a barrier of forms and codes.
Perhaps the affair is less about taxation than it is about trust. Trust that institutions can tell the difference between a commercial arrangement and a generous act. Trust that citizens will not exploit every available loophole. Trust that the law, though blind, can sometimes learn to navigate the edges of real life.
The retiree’s bees are still flying, incidentally.
What now lingers in the air above them is not merely the scent of wildflowers, but a national question: when a kind act meets an inflexible rule, which should yield first?
| Key point | Detail | Value for the reader |
|---|---|---|
| Written agreements matter | A straightforward, one-page document can demonstrate that you are a private landowner lending space rather than jointly operating a business | Lowers the risk of being wrongly reclassified as a professional farmer or operator |
| Declarations trigger classifications | When a professional declares your address as a place of work, algorithms may connect you with that activity | Helps you predict when a favour may create tax or social security consequences |
| Ask a few key questions upfront | Establish whether the use is professional, how long it will continue and who will declare what | Enables you to remain generous while protecting your finances and peace of mind |
Comments
No comments yet. Be the first to comment!
Leave a Comment