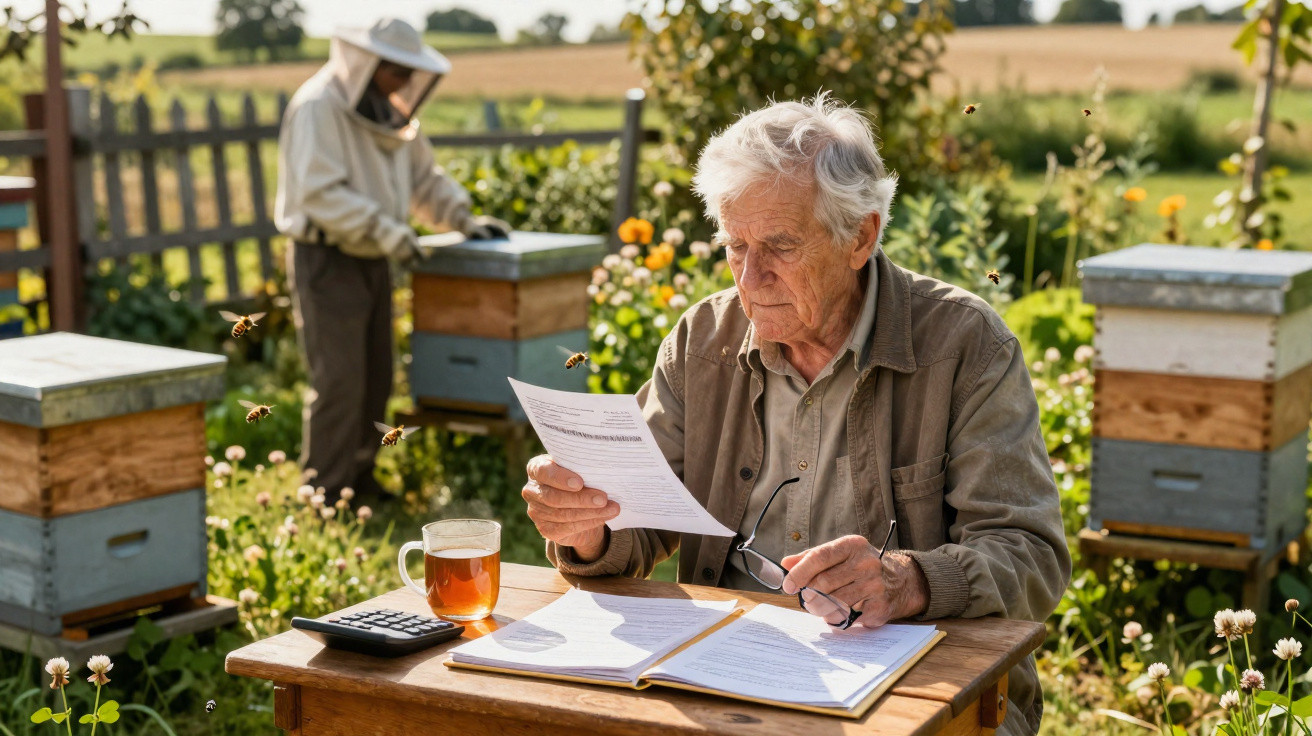
On a mild spring morning, as the air begins to buzz, Michael*, a 71-year-old pensioner, walks across his slim plot at the edge of a quiet village. The ground is not growing wheat or maize. Instead, a handful of wooden beehives stand there, their white paint flaking as bees move in and out with the steady rhythm of commuters at a tiny country station. Years earlier, he had allowed a local beekeeper to use the land free of charge, pleased to “do something for the bees” and bring life back to the site. There was no payment or formal contract: only a handshake and a smile.
Last month, however, an official envelope arrived through his letterbox. It contained a new agricultural tax assessment, with a sum due that exceeded his monthly pension supplement. He looked from the total to the description of his land as being in “agricultural use for production purposes”.
“I’m not making any money from this,” he said quietly.
When a few beehives make your garden a ‘farm’
In theory, the principle is straightforward: land used for farming or production is taxed as agricultural land. In practice, it is far less clear-cut in villages such as Michael’s. Pensioners may lend a corner of a plot to a young beekeeper, while a cousin might allow a neighbour to keep two goats behind the house. These small acts of generosity or environmental concern can suddenly be treated as taxable “activity”.
The tax office does not see the personal story or the informal agreement. It sees classifications, tick boxes and rates. As soon as a use is designated “agricultural”, a bill can follow, even where no money has passed between the landowner and the beekeeper. The beekeeper sells honey, the state measures the hectares, and the person caught between them receives the sting.
Consider a case that has been shared discreetly in rural Facebook groups. A retired widow living outside a medium-sized town allowed a hobby beekeeper to install six hives in her unused orchard. She asked for nothing in return, while he offered to bring her a few jars of honey every year. After two seasons, her agricultural land tax was reassessed and she received a late-payment fine because the plot’s “actual use” had shifted from “garden” to “productive agricultural land”.
At the local tax office, she explained that she was not a farmer, did not even own a veil or smoker, and simply liked bees. The clerk referred politely to the relevant code articles, adding gently that “this is happening a lot now”. Technically, the beekeeper was too small-scale and informal to register as a full agricultural business. The simplest person to pursue was therefore the individual named in the land register.
These personal cases reflect a quieter administrative change. Under pressure to fill budget shortfalls and bring property records into line, authorities have begun cross-checking satellite imagery, agricultural subsidies and land registries. Where they identify hives or cultivated plots, they are inclined to reclassify the land. The legislation does not necessarily consider whether the owner is earning an income.
In principle, this form of taxation is intended to be fair: land generating income should contribute towards public services. In reality, a growing grey area includes semi-urban gardens, inherited fields, tiny plots used for eco projects and hobby beekeeping. Such places sit uneasily between private enthusiasm and professional activity. In that uncertainty, small owners such as Michael are finding out how harsh broad tax categories can feel.
Protecting yourself when lending land for bees or ‘friendly farming’
When you are considering offering land to a beekeeper, market gardener or even a neighbour with sheep, trust is usually the starting point. It may begin with coffee around the kitchen table, an excited discussion about biodiversity and a walk around the ground. That personal connection matters. The next step, though, should be rather less exciting: put the arrangement in writing.
A brief and straightforward agreement can establish a great deal. It can state that the arrangement is non-commercial for you, that all beekeeping or farming income belongs to the other party, and that they are responsible for registrations connected with the activity. It may feel overly formal at the time. Nevertheless, a two-page agreement signed in spring could be the difference between a rewarding project and an alarming letter three years later.
Many people assume that, if no money changes hands, the tax office will take no interest. That can be reassuring, and it may remain true for years. But a local land-use review or a satellite-mapping programme can begin, and the position may quickly change. In truth, almost nobody studies the small print of land classifications until a difficulty arises.
A small landowner will often minimise what is taking place on the plot: “Oh, it’s just a few hives”, or “It’s just my nephew growing vegetables”. Tax law rarely gives much weight to “just”. What matters is the nature of the use, rather than how informal it appears. If you are lending land, asking a local beekeeping or small-farming association which paperwork it uses is not paranoia. It is self-defence in polite clothes.
We’ve all been there, that moment when a generous impulse collides with a system that speaks another language entirely. You may want to help bees or support a young producer, only to find yourself trying to interpret forms you hoped never to encounter again after retirement.
“I feel like I’m being punished for doing the right thing,” says Michael. “If I’d just left the field empty, full of weeds, nobody would bother me. But because there are bees and flowers, I get a tax bill. Where’s the logic in that?”
One useful way of reducing the risk is to use existing arrangements instead of relying on private handshake deals:
- Use written loan agreements, including template versions supplied by farming or beekeeping unions.
- Check local thresholds separating “professional” and “hobby” activity before hives or animals arrive.
- Ask your tax office in writing how the intended use will affect your land classification.
- Think about short, clearly seasonal agreements rather than open-ended arrangements.
- Speak to neighbours who already host hives to learn from their letters and inspections.
Bees, budgets and a changing countryside
The experience of small landowners and back-garden beekeepers reveals much about today’s countryside. On one side is a genuine appetite for local food, pollinators and low-impact farming, with people bringing neglected land back into use. On the other are strained public finances, tax systems created decades ago and digital tools that view plots as pixels and categories rather than favours exchanged between neighbours.
For many pensioners, land is not a business asset but a store of memories. It may be where children once played, parents planted trees or a dog lies buried beneath an old apple tree. Reducing that place to an Excel entry labelled “agricultural tax base” can feel harsh. Yet the beekeeper or small farmer using it may also be in a precarious position, trying to navigate rules never designed for someone with 10 hives and a second job.
Who ought to bear the cost of “saving the bees”: the modest landowner, the micro-beekeeper, the consumer buying honey or the state levying the tax? There is no simple answer. Even so, these quiet cases and their unexpected bills may prompt a broader reconsideration of how land use is taxed, as the distinctions between hobby, side hustle and farm become less clear every year.
| Key point | Detail | Value for the reader |
|---|---|---|
| Hidden reclassification risk | Land informally lent for bees or small-scale farming may be reclassified as agricultural land and taxed | Helps you foresee and avoid unexpected tax bills on “inactive” plots |
| Value of simple agreements | Short written contracts can establish who operates the activity and who carries tax and administrative responsibilities | Gives you a practical way to protect yourself while continuing to let others use your land |
| Check before lending | Confirming thresholds and classifications with local authorities or unions before hives arrive | Allows you to retain the benefits of bees and micro-farming without entering avoidable red tape |
Comments
No comments yet. Be the first to comment!
Leave a Comment