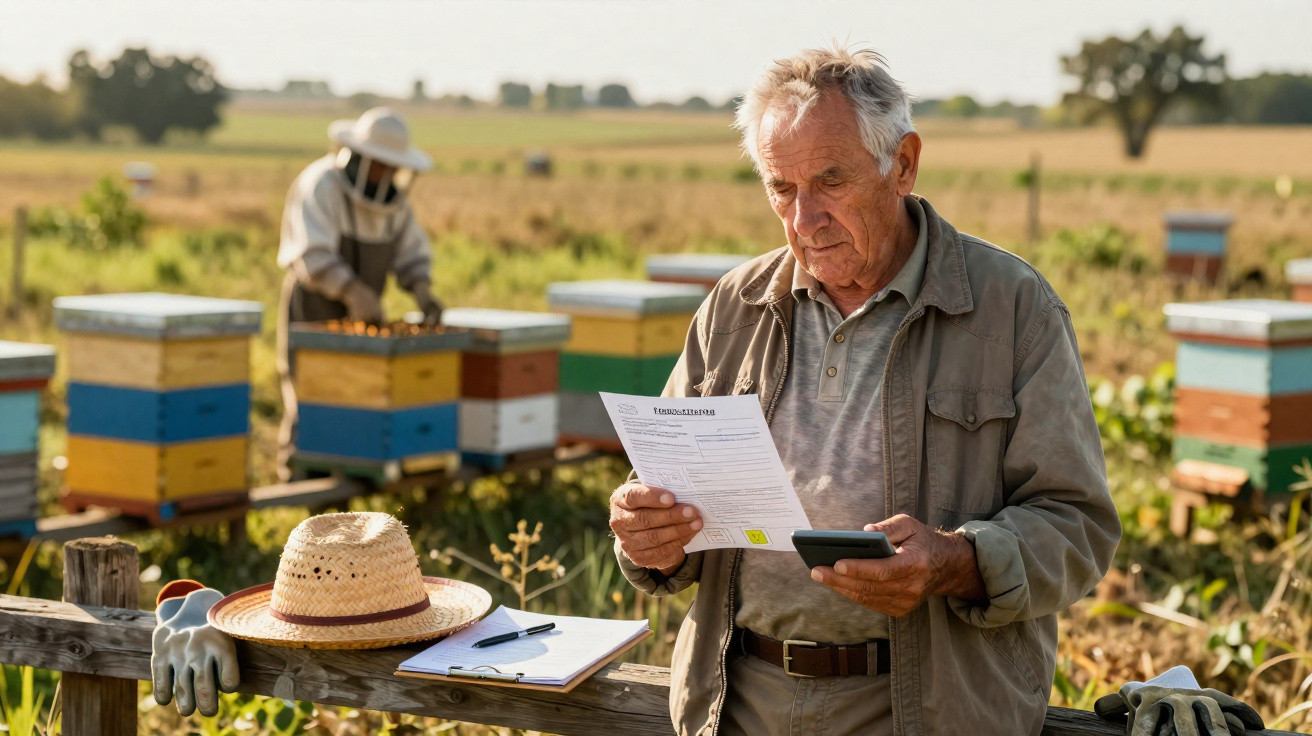
On a wet spring morning in the countryside, with grass sticking to his boots, Gérard gazed across his empty field and thought, “It’s a shame it’s just sitting there.”
A retired mechanic living on a modest pension, he had plenty of time but had watched nearby farms struggle. Shutters had closed one after another, while tractors slowly rusted away in back yards.
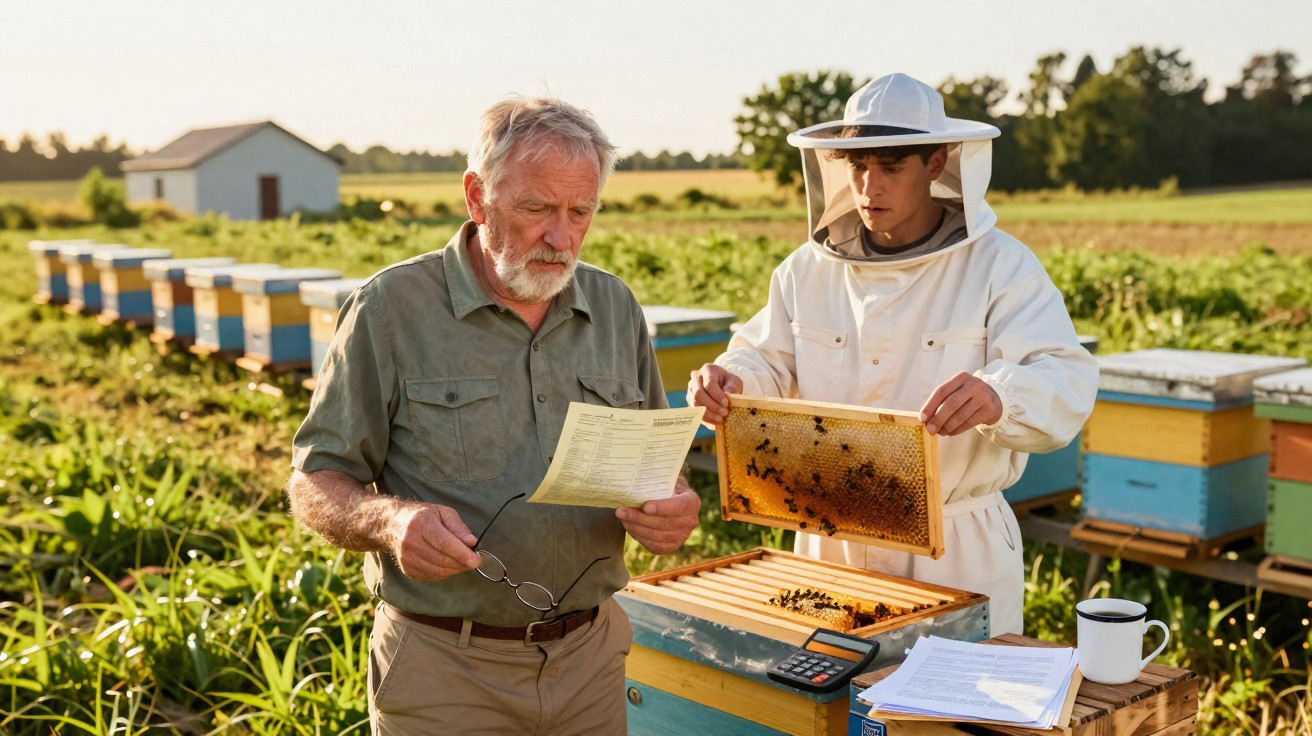
So, when Léa, a young beekeeper, called by and timidly asked whether she could keep several hives on his unused land “for nothing”, he agreed without a moment’s hesitation.
“No rent, just bring me a jar of honey from time to time,” he joked.
A few months later, the honey turned up.
Then so did something else.
A stark white envelope from the tax office.
That was the point at which a favour became a dispute.
When generosity meets the taxman’s calculator
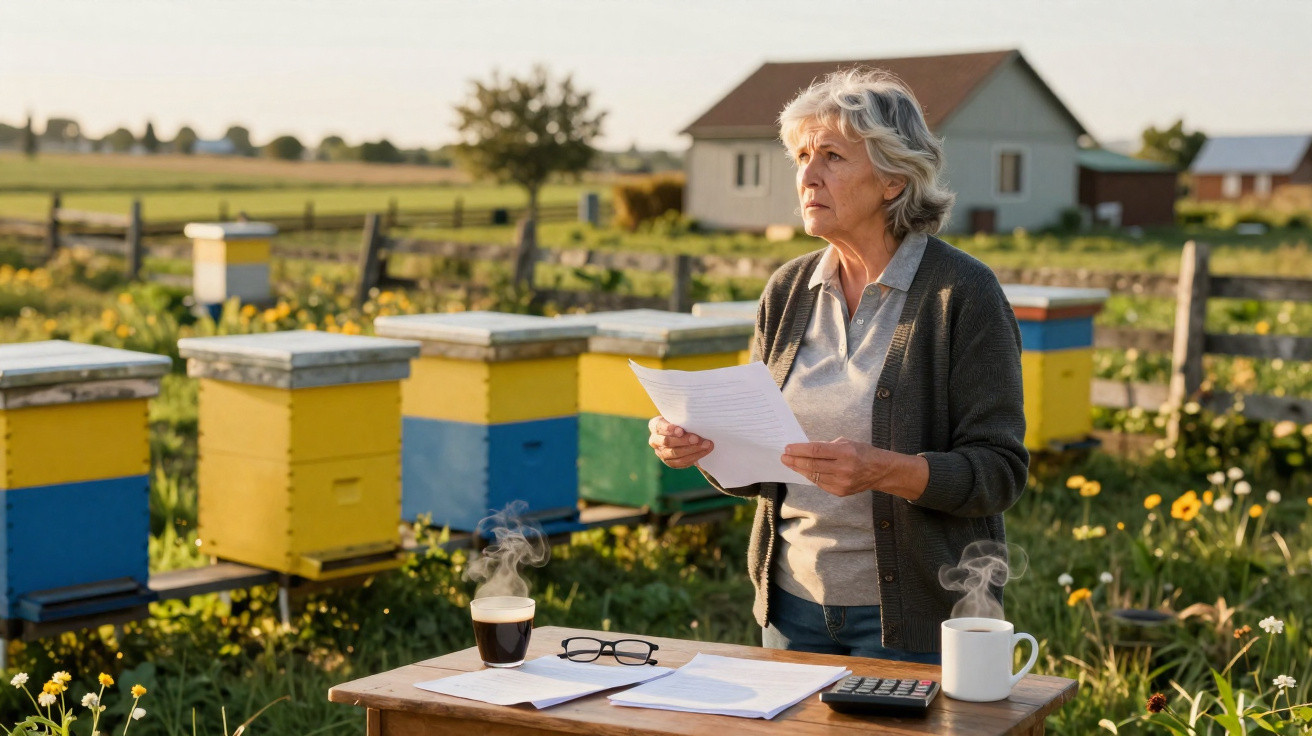
The letter used the sort of cold administrative language that can ruin a day instantly. Gérard read it three times before the meaning sank in: although his field was registered as agricultural land, it was now deemed to be used for professional activity.
Léa was not paying rent, yet the dozens of hives had prompted a reassessment. The tax office had classified the plot as “productive land” and expected payment.
He looked at the amount in disbelief. He had not made a penny. Even so, he now owed money for the supposed privilege of helping another person stay afloat.
For Gérard, it had all started with an ordinary chat at the local market. Léa sold jars bearing handwritten labels and explained that she had lost one of her sites after its owner chose to build tourist cabins there.
Her bees required a new place to live. She could not afford rent: her small business was barely surviving amid pesticides, drought and price competition from supermarkets.
Gérard therefore offered her his unused field. There was no formal agreement, no discussion of sharing income and no suggestion that the state could intervene between his grass and her bees. It simply seemed sensible: old-fashioned neighbourly support.
A year later, inspectors passed by, spotted the orderly rows of hives and connected the land registry entry with active agricultural use. The tax rules then took over.
This individual problem reflects a wider, less visible reality. Whenever land begins to appear commercially used, its tax treatment may change unexpectedly.
Agricultural classifications, local land taxes and thresholds for business activity can become tangled in legal wording that most pensioners and small-scale producers never fully examine. What seemed an innocent favour to a struggling beekeeper appeared, from the state’s viewpoint, to be a miniature agricultural business arrangement: a landowner, a professional user of the plot and the possibility of profit.
In principle, the law does not seek to penalise kindness. In reality, the system assesses activity rather than intention. When those two things clash, the taxpayer usually learns the lesson the hard way.
How to lend land without falling into a fiscal beehive
If you own a small piece of land, an orchard or a strip of pasture, it can be very tempting to let somebody use it rather than mow it twice a year. A neighbour with sheep, a gardener or a beekeeper: it can feel as straightforward as lending someone a book.
The first discreet way to protect yourself is remarkably simple: put the arrangement in writing. Produce a brief, clear document setting out who will use the land, what they will use it for and on which terms.
It need not be a 20-page legal contract. A two-page document signed by both parties can establish that the arrangement is a free loan rather than a concealed business partnership. Those few sentences may later help distinguish your position from that of the person actually making money.
The problem Gérard encountered is not unusual: people mistake generosity for a lack of risk. “No money changes hands, so I’m safe,” we tell ourselves. That is precisely where many landowners run into trouble.
Tax offices and local authorities do not assess rent alone. They also consider how the land is used, how regularly it is used and whether somebody is carrying out an activity that could be viewed as professional.
Seeking advice locally before allowing hives, vegetable plots or grazing animals may sound overly cautious. Honestly, hardly anyone does it every day. Yet a single short meeting with a local agricultural office or tax centre can prevent years of frustration - and thousands of euros in costs.
“People think if they don’t take rent, there’s nothing to declare,” sighs a rural tax advisor I spoke with.
“That’s not how the system reads it. The law looks at who benefits economically and how the land is used. And when it’s unclear, both sides can end up with problems.”
- Confirm the land’s status: is it officially agricultural, residential or something else?
- Record the favour in writing: use a simple free-use agreement, dated and signed by both people.
- Establish who is the professional: the beekeeper or farmer should hold the business status, rather than the landowner.
- Check local requirements: certain areas apply specific thresholds for agricultural or semi-professional activities.
- Retain evidence that any exchange is symbolic: a few jars of honey, rather than a recurring cash payment.
Who really profits when kindness gets taxed?
Gérard and Léa’s experience leaves a sour taste that extends well beyond the jars of honey. He feels let down by a state that demanded tax on income he never received. She feels caught between appreciation and guilt, questioning whether her precarious business has harmed the one person who offered help.
Neighbours discuss it in the café. Some fault the tax office; others argue that Gérard should have “checked first”; still others mutter that rules are rules and that land is never genuinely free. Underneath the conversation is a broader anxiety: when the state enters an arrangement based on private generosity, is it merely regulating it, or changing how willing people are to help one another?
| Key point | Detail | Value for the reader |
|---|---|---|
| Clarify land use | Understand whether your plot is regarded as agricultural, residential or mixed-use | Prevent unpleasant surprises when activity begins on your land |
| Put favours in writing | A simple free-use or loan agreement setting out rights and boundaries | Safeguards both you and the person you are helping |
| Seek local advice | A brief consultation with a tax office, farmers’ union or notary | Makes a risky “favour” into a clear, low-stress arrangement |
FAQ:
- Question 1 Can I lend land to a beekeeper without paying extra tax?
- Question 2 Must I declare a favour if I receive no rent?
- Question 3 What written document is sufficient for a “free loan” of land?
- Question 4 Can the beekeeper be treated as the sole professional, rather than me as the owner?
- Question 5 Which simple checks should I carry out before allowing somebody to use my field?
Comments
No comments yet. Be the first to comment!
Leave a Comment