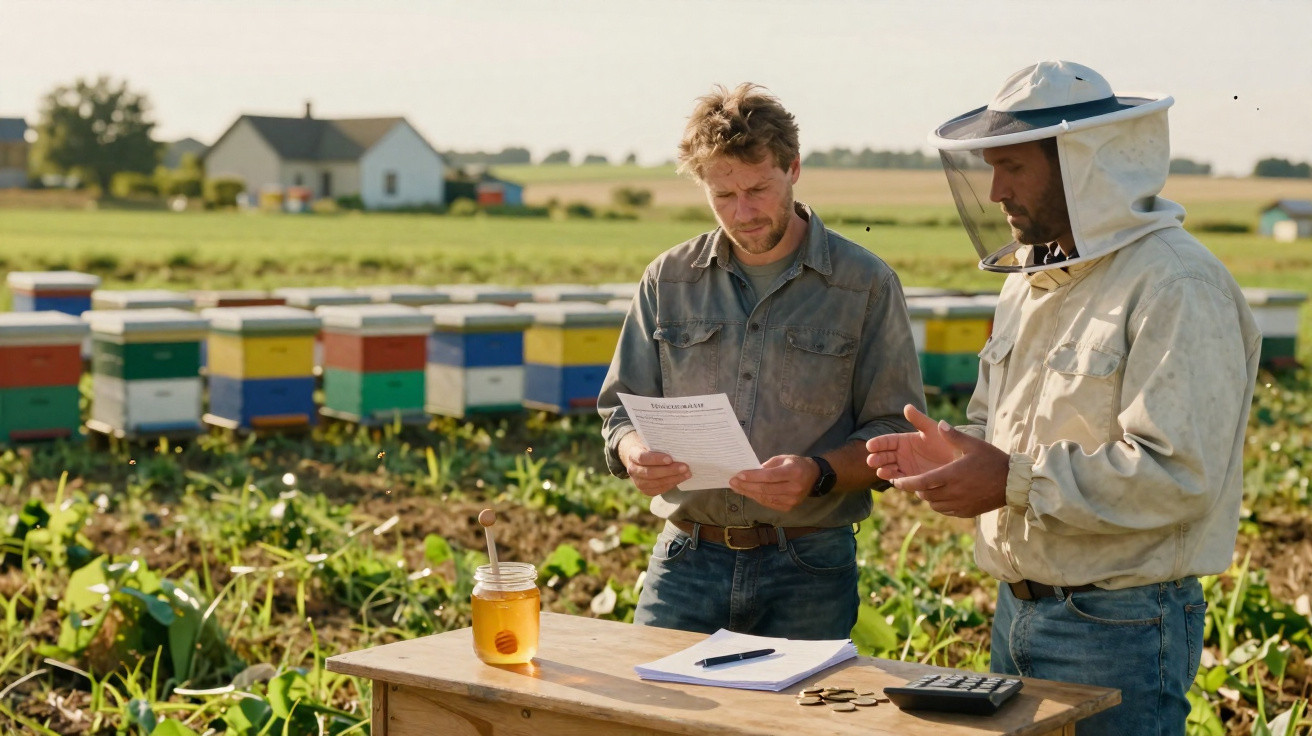
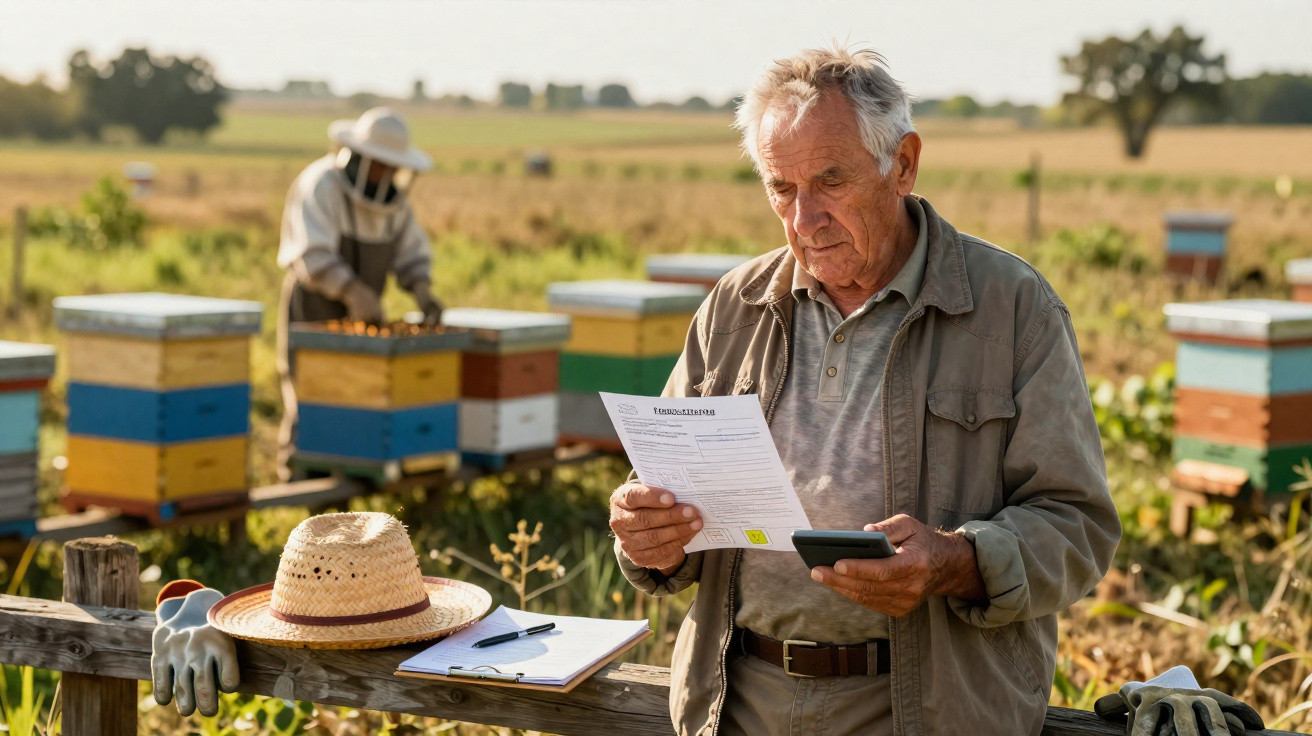
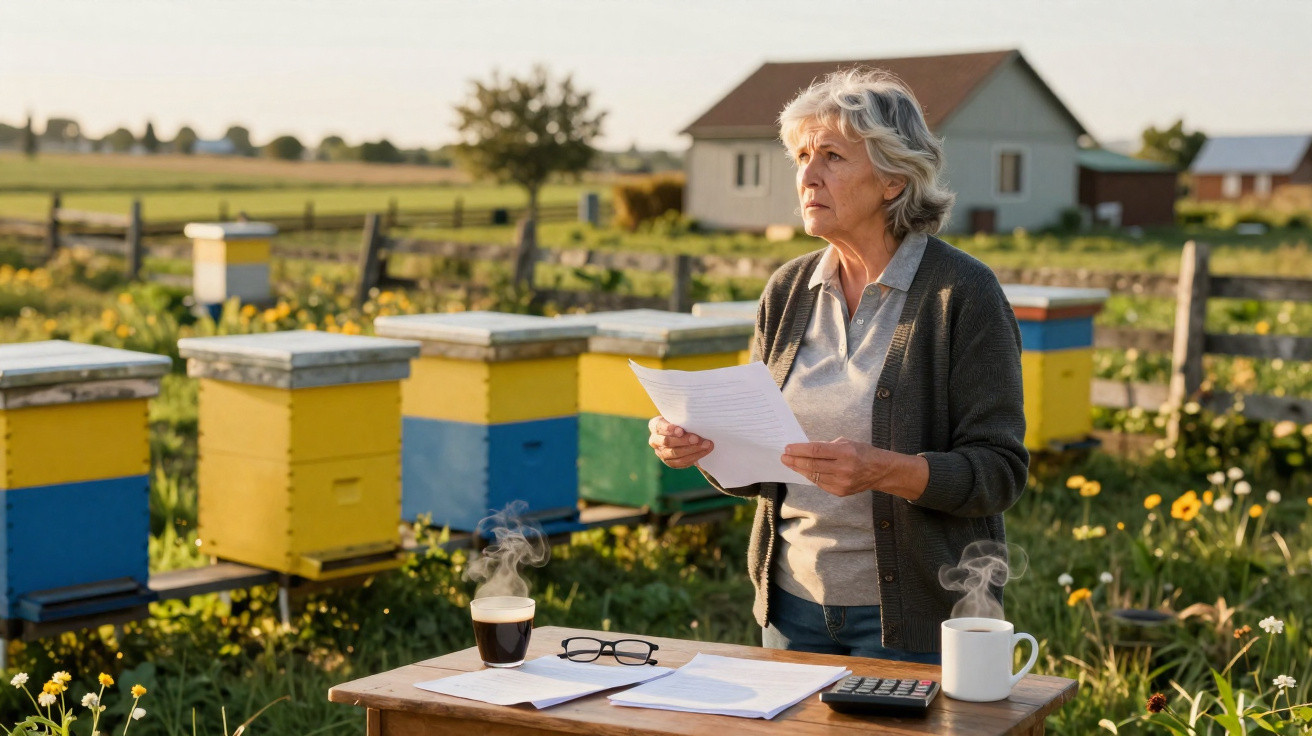
The story starts with a phone call that seems almost ridiculous. A homeowner in a quiet village, pleased with his modest plot and his new “eco-friendly” initiative, had allowed a local beekeeper to position hives in one corner of his land a year earlier. There was no rent: only the prospect of free jars of honey and the satisfying sense of helping the planet. Then the tax demand arrived. Agricultural tax on a property he regarded as “non-agricultural”. Every line carried his name. Not the beekeeper’s. Not the person selling the honey. His.
The dispute that came next was far from sweet.
On one side was a homeowner shocked by a tax charge he had never expected. On the other stood a beekeeper who maintained that the arrangement was “win-win”.
Clearly, somebody was coming out ahead.
When bees land on your lawn, the tax office takes notice
On the surface, the deal appeared straightforward: a narrow piece of land, a handshake and several hives tucked beside a hedge, barely visible from the road. The beekeeper visits a few times each month, inspects the frames, puts boxes of honey into his van and leaves with a friendly wave. To an outsider, it looks like an innocent rural arrangement.
For the tax authorities, however, those white boxes are more than simply boxes.
They indicate agricultural use.
In many areas, once land is deemed to be used for agriculture, its owner may be treated as an “agricultural taxpayer” - even if they have never put on a beekeeper’s suit.
Consider Marc, 52, who owns a house on the outskirts of a small town. He let a beekeeper friend use a tiny patch behind his hedges for a token payment: one euro a year and a couple of jars of honey at Christmas. There was no formal contract, merely a friendly written note and several WhatsApp photos taken when the hives were installed.
A year later, his property tax increased. There was a charge he had never previously encountered: tax calculated on agricultural use of land. At first, he assumed an administrative mistake had been made. The tax office took a different view.
It explained that, while the land stayed in his name and the activity was agricultural, he remained liable. When he rang the beekeeper, the discussion quickly became tense.
The sense of injustice is about more than the cost itself. Behind the arrangement, the roles can appear to be reversed. The beekeeper owns the hives, collects the honey and sells the jars at markets, at times accompanied by an appealing story about a “local partnership”.
The homeowner supplies the vital resource: the land, access to it and long-term security.
Yet under many tax systems, the person growing crops or keeping animals on land does not automatically pay agricultural property-related tax. The law often follows the title deeds rather than the trail of honey. That disconnect is ideal ground for friction, unstated assumptions and, in some instances, a genuine financial loss for someone who simply “wanted to help the bees”.
Turning a “friendly arrangement” into a fair beekeeping agreement
Avoiding this type of difficulty begins well before the first hive arrives. The sensible approach is to regard that small area of land for what it becomes once bees are placed there: a site of economic activity. A 20-page contract is unnecessary, but a clear, binding document is needed.
Set out who is responsible for what, who pays which costs and who bears the consequences if the tax office reclassifies the land as agricultural. A single page, dated and signed by both parties, may be enough.
It should contain a clause expressly covering tax responsibilities and possible reclassification. That might seem overly formal for “a few boxes of bees”, but it may be the clause that protects your finances later.
Many homeowners caught in this position accuse themselves of being gullible. The reality is kinder: they behaved as neighbours rather than solicitors. Few people would expect six hives at the end of a garden to result in an unforeseen tax demand.
The biggest pitfall is the familiar “don’t worry, it’s just symbolic” attitude. Symbolic rent. Symbolic use. Symbolic agreement. The beekeeper avoids land costs, the homeowner feels charitable, and nobody works out who is taking on each risk.
In truth, no one studies the tax code every time they lend a friend a corner of their land.
But the tax office is unconcerned whether rent is paid in euros or honey jars. The land is being used, the owner is known, and the demand follows the name on the deeds. That is the point at which good intentions give way to paperwork.
At the centre of the disagreement between a homeowner and a beekeeper is often an unclear view of who actually benefits from the hives. The immediate response is usually, “the beekeeper, of course, he sells the honey.” Yet the reality is more complicated.
“From my side, I bring the hives, the equipment, the time, the risk of disease, and the work every weekend,” one semi‑professional beekeeper told me. “The landowner gives me space, yes, but without me those hives don’t exist. We co‑create the value.”
In reality, three sources of gain and cost quietly emerge:
- The beekeeper’s direct earnings from honey and related products.
- The homeowner’s indirect advantages: a “greener” image, perhaps greater appeal for the property and, sometimes, free honey.
- The concealed cost: tax, insurance and possible land-use reclassification, which is almost always carried by the owner.
If nobody clearly identifies this three-way balance at the outset, silence later turns into resentment.
Who really benefits when bees move in?
This kind of neighbourhood dispute raises a broader and less comfortable issue: how should we divide the cost of environmental gestures that also operate as small businesses? Letting land to a beekeeper can feel like an ecological act, much like planting a tree or putting up a bird feeder. Once the tax bill arrives, though, the gesture can start to look like a private subsidy for somebody else’s enterprise.
Some homeowners accept the expense and retain the hives, reassuring themselves that it is “for nature”. Others remove the hives, end the relationship and decide never again to combine friendship, land and money. Both responses make sense.
Somewhere between those positions is a more mature perspective.
Most of us know that moment when a pleasant, uncomplicated idea becomes burdensome as soon as the first official letter appears. The appeal disappears immediately. The relationship deteriorates, not because either person intended harm, but because neither anticipated that the State would be sitting invisibly at the table as well.
The straightforward reality is that bees are not merely poetic. They are an agricultural resource. Once that classification applies, administration soon follows.
Perhaps, then, the more useful question is not “who profits from the hives?” but “who agrees to be formally connected to the activity on paper?”. It is the person named on the deeds, forms and database - the one whose letterbox receives the brown envelopes.
Stories like this travel quickly through villages and suburbs. One unhappy experience may be enough to make three other neighbours hesitate before agreeing to a friendly beekeeper’s request. Some will now insist on written agreements, shared tax payments or a modest rent that properly reflects the risk. Others will argue that associations or local authorities should place hives on public land, spreading rather than concentrating the individual burden.
There is no simple formula, nor any magic contract clause that can prevent every dispute. Still, each story prompts a distinctly modern discussion about how land is valued, how “good deeds” are priced and how rapidly a jar of honey can become a symbol of broken trust.
The sound of buzzing in the garden suddenly feels very different.
| Key point | Detail | Value for the reader |
|---|---|---|
| Clarify tax risk early | Any agricultural use of your land may result in reclassification and additional tax in your name | Identify likely costs before accepting hives or comparable activities |
| Put agreements in writing | Straightforward one-page contracts should cover tax, responsibilities and duration | Limit disputes and provide a basis for negotiation if a disagreement arises |
| Balance profit and burden | Agree how honey sales, free products, rent and tax will be divided | Create fairer arrangements and reduce surprises for homeowner and beekeeper alike |
Comments
No comments yet. Be the first to comment!
Leave a Comment