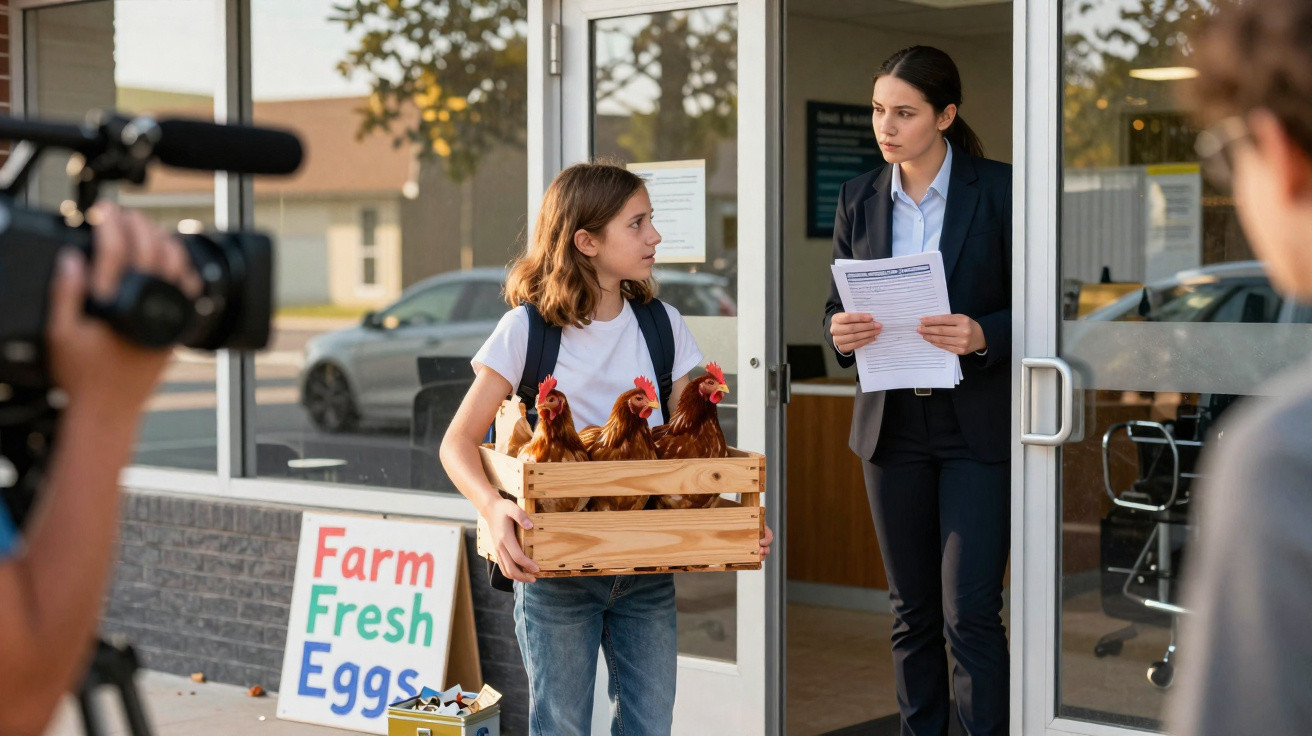
A schoolgirl in the United States experiences her first financial scandal.
A ten-year-old from Arizona simply wanted to rear some chickens and sell them at a rural fair. It became a modest financial success story – until her bank froze the cheque, blocked the account and kept the girl from receiving the money she had earned for months. The family’s dispute eventually reached the media, putting considerable pressure on the bank.
How a hobby with chickens became a serious venture
Kinley Maner lives in the countryside near the small Arizona town of Thatcher. She loves animals and persuaded her parents to let her keep chickens. At first, it appeared to be an ordinary childhood pastime: a few chicks, feed and cleaning out the coop. Her father also regarded it as an opportunity to teach his daughter responsibility.
Before long, it developed into something more substantial. The area holds a county fair where children and young people can display and auction their animals. Kinley chose to take part and raised her chickens specifically for the event. She got up early, fed them, cleaned up after them and looked after their health. To her family, this was clearly no longer just play; it was real work.
Cute chicks become a serious project – with real money at the end.
At the Graham County fair, Kinley showed her six chickens. She answered the judges’ questions, demonstrated how she cared for the birds and presented herself confidently. The auction that followed exceeded every expectation: together, the animals fetched around €1,900 – an enormous amount for a child.
From the fair straight into trouble with the bank
The proceeds were paid not in cash but by cheque. The treasurer of the local breeding association correctly issued the document in Kinley’s name. Her parents decided to deposit the cheque into her mother’s account with major bank Chase. The money was intended to be kept safely there, with most of it later going into an education fund.
That is precisely where the difficulties began. The bank considered the cheque suspicious. It claimed that the contact telephone number for the issuing association could not be reached. Rather than investigating further, the institution opted to freeze the account and block the cheque.
The parents suddenly faced a barrier of forms, automated hotline messages and inflexible procedures. Kinley’s mother spent hours on hold, trying to explain the situation, offering to provide documents and contacts at the association. Meanwhile, the treasurer also visited the branch several times to verify the cheque – without success.
The bank preferred its rigid system to real people on the ground.
Instead of a practical resolution, the family received only standard responses: the matter was under review, the number could not be contacted and the funds could not be released. To them, it felt as though the bank had simply withheld the child’s money.
A year of waiting: when a child learns how tough banks can be
A year passed. Kinley grew older, her chickens had long since been sold, but the money still had not appeared in the account. She understood only the basics of what had happened: she had worked hard, looked after the animals and stood at the fair – yet received nothing in return.
For a child, it was a painful lesson. Instead of pride and encouragement, she was left with frustration and the feeling that nobody took her seriously. Her parents openly described the situation as plainly unfair. In their view, a powerful bank was refusing a girl the money she had honestly earned because its internal rules mattered more than common sense.
- Child’s age: 10 years at the start of the project
- Number of chickens: 6 animals
- Auction proceeds: approx. €1,900
- Time until the money was released: around one year
- Cause of the problem: doubts about the cheque’s authenticity
Media attention moves the case forward
Once the family realised that polite telephone calls were achieving nothing, they took a different approach: they brought the story to a regional television station. The plight of a ten-year-old unable to access her money because of rigid bank procedures appeared on television, bringing it into public debate.
The situation suddenly became uncomfortable for the bank. A major brand can quickly seem heartless when a report portrays it as opposing a child. Shortly after the broadcast, the institution responded. Those responsible apologised, the account was reopened and the cheque was finally credited.
Once the cameras are rolling, what was “impossible” for a year suddenly becomes possible.
Kinley did eventually receive her money. She was surprised and relieved. Part of it is to be invested for the long term, for example towards future university costs. She plans to use the remainder for smaller things a child enjoys – without any guilt, because she genuinely earned the money.
What the case reveals about banks and young customers
Stories such as this show how far large financial institutions can become removed from the everyday reality of their customers. Fraud prevention is sensible in principle, especially with cheques and unusual incoming payments. Yet when a local association, the parents and the issuer all appear in person at the branch several times and a flexible approach is still impossible, something has gone wrong.
Cases like this illustrate how heavily automated checking systems shape everyday life. Algorithms flag a transaction as suspicious, call-centre staff have very limited authority, and branches are constrained by liability concerns and rigid rules. In the end, the person affected is not a fraudster but a child who has learned responsibility and now distrusts the financial system.
How children in Germany and Europe are allowed to earn money
The case took place in the United States, but it also raises questions in German-speaking countries: what are the rules here when children earn money themselves? Many European countries have strict requirements for minors. In Germany, children under 13 may work only to a very limited extent, and even small jobs are closely monitored by the authorities. Helping on a family farm or taking part in association projects often falls into the category of a hobby or voluntary activity.
From a certain age, holiday jobs are permitted, subject to clearly limited working hours and types of work. The aim is to protect children and young people: education and health should take priority, while economic exploitation must be prevented. At the same time, this raises the question of how young people can learn to handle money and their own work responsibly.
| Age | Typical rules |
|---|---|
| Under 13 years | Only very limited activities, usually in artistic or family settings |
| 13–15 years | Light, safe work, limited hours, often only during school holidays |
| From 16 years | More employment options, but still clear limits on working hours and night work |
Who owns money earned by minors?
In legal terms, parents generally manage their children’s assets. They are expected to act carefully and preserve the capital. Income from smaller activities – such as holiday jobs or minor projects – often goes into children’s or family accounts. Where larger sums are involved, it makes sense to agree clear arrangements: how much will be saved, how much may be spent and on what exactly?
The Arizona case demonstrates how important it is to be transparent with children. Kinley knew how much her chickens had earned. She could therefore clearly state what was due to her. Many children in Europe barely know the balance in their savings account or do not understand what happens to their money. Those who take children seriously involve them in decisions early on – even when adults carry the legal responsibility.
What families can learn from this story
Parents planning similar projects can draw several lessons from it. Before undertaking a larger activity, it is worth speaking to the bank: how are cheques handled? What evidence is required? Are there children’s or young people’s accounts designed for this sort of income? The more questions are resolved in advance, the lower the risk of later becoming bogged down in bureaucracy.
The story also shows that public attention can be a powerful source of pressure. Anyone who believes they are in the right but cannot make progress with a large institution can involve the media or consumer organisations. Companies often react more sensitively once a case reaches a wider audience, particularly when minors are involved.
And for children such as Kinley, one important lesson remains despite everything: their own work has value. Sometimes patience and persistence are needed before the payment truly reaches the account – but that can also foster a highly realistic understanding of money, responsibility and power dynamics in everyday life.
Comments
No comments yet. Be the first to comment!
Leave a Comment